A Payroll Solutions Portal helps organizations centralize payroll workflows, compliance checks, and employee self-service in one secure place. This guide explains what such a portal is, how vendors typically structure pricing and implementation, and how to evaluate supplier fit objectively—so HR, finance, and IT can reduce errors while improving transparency.
A Payroll Solutions Portal is very valuable when it becomes the operational “control tower” for payroll processes—streamlining data flow, improving auditability, and enabling employee self-service (for example, accessing pay information and important payroll communications) without forcing staff to chase emails or spreadsheets. In practice, the top outcomes come from aligning the portal’s capabilities with your organization’s compliance requirements, identity/security model, pay-run workflows, and reporting needs.
When selecting a portal, focus first on the parts that affect payroll accuracy and governance: role-based access, validated integration paths (HRIS/ERP), change tracking for payroll inputs, and the ability to support consistent compliance workflows. From there, you can evaluate usability (employee experience), operational fit (administrative workload), and scalability (how the portal behaves as you add entities or expand headcount).
It helps to frame the portal as an operating model—because payroll is not only a software problem, it’s a process problem. A portal that looks good in a demo but does not map to your reality will still create friction: data may arrive late, approvals may occur too late, exceptions may not be logged, and reporting may not reconcile to the numbers finance needs for posting. Conversely, a portal that is tightly aligned to your current processes (and can evolve them safely) can reduce risk and workload at the same time.
From HR’s perspective, the portal should reduce the “invisible labor” around payroll: clarifying what employees need to do before payroll cutoffs, preventing repetitive question handling, and ensuring HR admins know exactly what data changes are allowed and how those changes are reflected in the next pay run. From finance’s perspective, the portal should preserve traceability and consistency—showing what payroll inputs were used, when approvals occurred, what adjustments were made, and what exceptions were resolved. From IT’s perspective, it should be secure by design: consistent identity integration, well-defined integration patterns, manageable configurations, and evidence suitable for internal risk reviews.
Finally, consider the behavioral dimension: will people actually use the portal? If employees still rely on email because the portal requires too many clicks or doesn’t clearly explain eligibility, the organization may not get the operational benefit. If HR admins avoid the portal because the workflow is confusing or the approval steps are unclear, the organization will revert to spreadsheets and manual corrections—defeating the purpose. The best portals are those that make “the right way” easy and “the risky way” hard.
Payroll is both transaction-heavy and compliance-sensitive, which creates recurring pressure on organizations to reduce manual rework and strengthen oversight. A portal approach addresses common pain points across HR and finance teams—such as version control problems, unclear ownership of payroll data changes, and limited visibility into who updated what and when.
In many organizations, payroll operations grew over time. For example, employee details might be updated in the HRIS, exceptions might be handled in ticket systems, payroll notices might be sent by email, and approvals might happen in email threads or chat messages. Even if every individual step is reasonable on its own, the overall process can become fragile: updates may be inconsistent, audit trails may be incomplete, and it can be difficult to reconstruct what happened for an employee or for a specific pay run.
In addition, modern workforce expectations are shifting toward self-service and faster resolution of routine questions (e.g., “Where can I view my payslip?” “How do I update certain personal details for payroll processing?”). A well-designed Payroll Solutions Portal can reduce ticket volume by providing consistent employee-facing information and guided actions.
Another objective driver is control over change. Payroll inputs change frequently: new hires, terminations, address changes, bank updates, tax elections, benefit selections, and adjustments after payroll has closed. Without a portal that can govern who may change what, organizations tend to rely on ad-hoc requests and manual interventions. This not only increases workload but can also introduce errors—especially when multiple HR users update payroll-relevant fields without standardized validation or approval logic.
Finally, adoption is often motivated by audit and governance pressure. Whether you are responding to internal audit findings, external regulatory requirements, or simply improving operational maturity, the portal can provide a structured way to demonstrate evidence: approval steps, data change logs, timestamps, and version histories. That evidence becomes crucial when something goes wrong or when you need to show that processes were followed consistently.
Below are the capability areas that typically differentiate portal offerings. Treat these as evaluation criteria rather than marketing claims—your internal stakeholders can map each requirement to what the supplier demonstrates during discovery.
From an expert perspective, it’s not enough for a portal to “have features.” The critical question is whether the features match your real pay-cycle: how employees are added, how changes are captured, who approves exceptions, and how payroll outputs are reconciled and posted downstream.
To evaluate each capability, translate it into operational scenarios. For example:
Those scenarios help you detect whether the portal is truly designed for payroll realities. A general workflow tool might look similar on the surface, but payroll requires specialized controls: specific validation rules, cutoff handling, evidence retention, and strong traceability between input changes and output results.
Also consider operational governance features that often get overlooked in early evaluations:
These elements matter because they connect portal functionality to everyday governance. Without them, payroll operations may still run outside the portal, resulting in gaps in auditability and inconsistent processing.
You’ll often encounter a pricing model for a Payroll Solutions Portal that includes one or more of the following elements: licensing per organization, per employee, per payroll run, implementation services, and ongoing support tiers. Because specific numbers depend heavily on scope (modules, integrations, security requirements, and compliance scope), the very objective approach is to request an itemized proposal and compare total cost of ownership rather than focusing on the first quote.
When evaluating cost, ask suppliers to break pricing into: (1) portal module licensing, (2) implementation and configuration, (3) integration work (if any), (4) data migration scope, (5) training, (6) support/maintenance, and (7) any optional add-ons (e.g., advanced reporting, additional self-service features, or enhanced security controls).
One important condition: ensure that the pricing includes the operational responsibilities you expect. For example, if employee self-service requires workflow ownership or content governance, confirm who maintains portal templates, notifications, and policy wording over time.
To avoid surprises, also ask for clarity on what is included in ongoing support. Some vendors offer “support” that mainly means basic ticket handling for technical issues, while other vendors include operational guidance for payroll calendar changes, quarterly compliance updates, and configuration optimization. If the vendor expects your team to do those activities without included resources, the operational burden could increase even if the licensing cost seems reasonable.
When comparing total cost of ownership, include internal costs as well. Portals often require internal effort for:
A common failure pattern is underestimating how much governance work is required after go-live. Even after the portal is implemented, organizations must keep it accurate: ensure notices are correct, approval routes remain aligned to org changes, and reporting remains reliable. Those activities can be routine, but they must be resourced.
Another factor is scaling. If you have multiple countries, business units, or subsidiaries, examine whether pricing scales linearly with entities or whether there are additional per-entity fees for workflow configuration, language support, or reporting. Similarly, confirm whether add-ons are “small” in practice—some vendors price advanced audit exports or reconciliation dashboards as premium features, which can materially affect operational reporting needs.
Many organizations select a vendor based on demo quality. As an expert reviewer, I recommend validating delivery capability using practical evidence:
These checks matter because payroll projects often fail due to under-scoped integration work, insufficient testing, or unclear responsibilities between customer teams and the supplier.
To make due diligence more concrete, ask the supplier to provide references that match your situation. The strongest references are those with similar complexity: similar employee count, similar number of jurisdictions, similar payroll event complexity (retro pay, corrections), and similar integration complexity. If the supplier can show case studies where they handled issues like payroll calendar changes or integration failures, that is more valuable than generic success metrics.
Also verify the supplier’s approach to documentation. For payroll governance, you need evidence: how workflows are configured, how approvals are recorded, how audit retention works, and how you can extract data when you need it for audits or internal investigations. Ask whether documentation includes:
Then validate that the supplier actually follows the process. Ask who will own each phase (requirements, configuration, testing, security review, training) and whether the supplier’s delivery team composition is stable or heavily dependent on short-term resourcing. Stable delivery teams often lead to higher consistency and fewer gaps.
Finally, verify risk management practices. Payroll implementations should include identified risks and mitigation plans—such as data quality issues during migration, integration mapping errors, identity/SSO problems, and communication mistakes that cause employee confusion. A vendor that can articulate these risks clearly is usually more prepared for real-world deployment.
Even before you sign, map your internal readiness. The very successful deployments treat the portal as a governed system, not merely a user interface. Use the steps below as a planning backbone; adapt to your organization’s pay-cycle and change controls.
To expand this into an implementation approach that actually works in enterprise environments, consider adding a governance layer that runs across all steps.
6A) Governance: set up a cross-functional operating team early
Create a payroll portal steering group that includes HR operations, payroll processing leadership, finance reconciliation leadership, IT security/integration representation, and ideally a representative from employee communications. The portal affects multiple stakeholders, so governance reduces the risk of decisions being made in isolated groups.
6B) Define “systems of record” and “systems of engagement”
A frequent ambiguity is where “truth” lives. For example, employee personal details may be “owned” by HRIS, while payroll outcomes are produced by payroll calculations and posted by finance. The portal may act as both an interaction layer (employee self-service) and a workflow layer (HR and finance approvals). In implementation, explicitly define:
6C) Create a pay-cycle calendar aligned to portal workflows
Because payroll has cutoffs, the portal must reflect the calendar: when employee changes are accepted, when approvals must be completed, and when corrections can still be applied. Implementation should map these cutoffs into the portal workflows and notifications.
6D) Design test cases around payroll exceptions, not only happy paths
Many teams test only standard scenarios: a new hire, a routine payroll run, a standard payslip view. But payroll issues often arise in exceptions. Include test cases for:
6E) Build a reconciliation strategy for finance
Finance requires confidence that payroll results can be reconciled for posting. Implementation should specify what finance expects: which exports, which reports, which totals should match which payroll registers, and how exceptions are represented. If the portal makes it easy to reconcile, adoption increases and operational risk decreases.
6F) Prepare operational runbooks
During go-live and steady state, runbooks reduce uncertainty. Runbooks should include steps for handling integration failures, identity problems, portal downtime scenarios, and emergency changes. They should also define escalation paths and communications procedures.
By treating implementation as an operating model—not only a technical deployment—you increase the chance that the portal will become the system people rely on during the payroll season.
A portal approach tends to deliver strong value when your organization has one or more of the following conditions:
Additionally, portals are particularly valuable when your organization has frequent change: reorganizations, mergers, acquisition integrations, new benefits programs, or frequent policy updates. In these contexts, a portal can provide a consistent interface for employees and a consistent workflow interface for administrators, reducing the chaos that typically accompanies policy or process changes.
Portals also help when you have distributed teams. For example, HR administrators may be distributed across time zones, while payroll close happens centrally. A portal enables standardized approvals and clear evidence, reducing reliance on synchronized email chains. Similarly, IT teams can manage access and integration consistently, improving security posture.
One more condition is the need for “controlled communication.” Employees often need payroll notices—such as tax form updates, payslip availability notices, policy updates, or explanation of deductions. If these communications are scattered across email, documents, and portals, employees might miss key information. A payroll portal can centralize and govern these communications, often with better tracking and consistency.
Payroll systems touch everyday life, so usability matters. Even within a single organization, HR teams often express that employees in different departments or locations need different levels of guidance—especially around pay timing, deductions, and how to submit eligible changes.
If you operate across multiple sites, consider localized training materials, language support, and role-specific documentation. Also, align portal communication with the rhythm of local HR culture: for example, in many organizations the period surrounding monthly payroll is a “peak season” for questions, so employee-facing guidance should be timed to reduce confusion (e.g., reminders about what to do before approvals or deadlines).
On employee experience, use plain-language labels for actions and avoid jargon in self-service screens. HR staff often notice that when the portal content is too technical, employees defer to email support rather than using the portal—negating some of the operational benefits.
Localization goes beyond translating words. Consider differences in:
Localization also affects governance. If employees can update personal details via the portal, the portal must enforce validation rules appropriate to local requirements. That means localization must be reflected in the rules engine and not only in the user interface language.
Another dimension is accessibility. In multinational organizations, employees may access payroll portals using mobile devices, assistive technologies, or different browsers. Implementation should include accessibility checks so that self-service becomes truly usable, not “technically available” but practically difficult.
Finally, consider localized support. Even with the same portal, local HR teams might provide different support channels (local HR email, local HR phone, internal ticket queues). You can improve employee resolution by integrating the portal with the support workflow—so that when employees need help, the system routes them appropriately and logs the request in a way administrators can use for troubleshooting and continuous improvement.
The table below summarizes common evaluation dimensions for a Payroll Solutions Portal by comparing practical implementation considerations. This is designed to help you structure supplier questions and internal approvals—without relying on promotional claims.
| Evaluation Dimension | What to Compare | Suggested Internal Condition/Requirement |
|---|---|---|
| Security model | Role-based access, audit logs, identity support | Define who can view, approve, and edit payroll inputs; verify auditability for key actions. |
| Workflow fit | Approval steps, exception handling, pay-run control | Match the portal workflow to your actual payroll calendar and approval hierarchy. |
| Integration approach | Data flows with HRIS/ERP/time systems | Confirm data mapping, validation rules, and error handling for integration failures. |
| Employee self-service | What employees can view/update and how changes are logged | Specify eligible actions and ensure updates follow validation + approval processes where required. |
| Reporting and audit evidence | Exports, dashboards, retention policies | Require evidence needed for audits and internal controls; confirm retention settings. |
| Implementation scope | Configuration, migration, testing, training services | Use an itemized scope statement to avoid hidden work during onboarding. |
| Support and continuity | Support hours, escalation, incident handling | Define response expectations during payroll close and go-live windows. |
| Total cost of ownership | Licensing + services + integration + ongoing maintenance | Compare total cost across a multi-year horizon; confirm what is included vs. optional. |
To make the comparison table more actionable, consider adding internal “must-have” and “nice-to-have” categories. Not every organization needs every portal capability on day one. But governance capabilities—like audit trails, role-based access, and reliable integration error handling—are typically must-haves in payroll contexts.
Also compare how suppliers demonstrate each dimension. For example, for reporting, require sample outputs based on your data model. For workflow fit, require a prototype or workshop walkthrough using real payroll events. For security, require documentation and evidence—not only claims. When suppliers can’t provide concrete demonstrations, you should treat the gap as a risk factor.
While each portal differs, the underlying governance principles are consistent across industry. For compliance and security practices, many organizations align their approach with recognized frameworks and guidance. For example, the U.S. National Institute of Standards and Technology (NIST) provides widely used guidance on security and risk management practices (see NIST publications and the NIST Cybersecurity Framework). Additionally, organizations often reference guidance on data protection and privacy controls from official sources and regulators relevant to their operating regions.
Because the specific jurisdiction for your payroll may vary, you should confirm requirements with qualified advisors and ensure that the portal’s documented controls align with applicable laws and regulations.
Source note: For general cybersecurity risk and control guidance, see the NIST Cybersecurity Framework and related NIST publications (U.S. National Institute of Standards and Technology). For privacy and data protection principles, consult official guidance issued by relevant regulators in your jurisdictions.
For “what good looks like” in an enterprise payroll portal, decision-makers typically look for four qualities working together:
In addition, good portals demonstrate operational maturity. That includes predictable release cycles, documented configuration changes, and the ability to support internal governance processes. If the portal makes it hard to identify the origin of a configuration or the reason a decision was approved, the portal becomes a compliance risk rather than a mitigation.
Decision-makers should also evaluate the portal’s role in the “end-to-end payroll chain.” Payroll is often downstream of time tracking, upstream of accounting posting, and connected to employee identity and communication. A good portal reduces seams between those systems by offering consistent data exchange and by making exceptions visible across the workflow.
One practical metric is reconciliation stability. If finance can reconcile payroll results to their ledgers consistently and can explain differences quickly, that typically indicates the portal’s evidence and exports are well designed. If reconciliation requires heavy manual effort or repeated custom extraction scripts, the portal may introduce new friction.
Another practical metric is support burden. If the portal reduces the number of routine employee tickets, HR admins should experience fewer interruptions. If employees still contact support because the portal doesn’t answer key questions, then you may need to strengthen portal content governance and improve self-service guidance.
To keep procurement objective, consider requiring suppliers to demonstrate the following in their pilot or solution workshop:
To strengthen your procurement position further, require written answers that include operational assumptions. For example: during cutoff, can HR edit data? During payroll close, what actions are blocked or restricted? If integration fails, does the portal create an exception ticket automatically? Are employees still able to access payslips if the portal is temporarily in degraded mode? These details define how the portal behaves under stress, which is when payroll operations suffer most.
Consider also requiring evidence of security posture in practical terms. Not only should you receive security documentation, but you should confirm what it means for payroll operations:
Additionally, clarify how the portal supports ongoing compliance updates. Payroll rules and reporting requirements change. Ask how updates are handled: are configuration changes versioned, reviewed, and tested? Are there standard release notes and can your organization control timing? A portal that updates without governance may create compliance risk.
Finally, define the “ownership of content” for employee self-service. Payroll portals often include notices and explanations. These materials should follow policy and legal requirements. Require suppliers to clarify:
These content governance requirements are not cosmetic. They reduce employee confusion and ensure employees receive accurate instructions that prevent payroll issues.
A Payroll Solutions Portal is a centralized system that supports payroll operations and employee self-service. It typically helps manage payroll workflows, permissions, and payroll-related communications, while maintaining auditability and controlled access to payroll-relevant information.
HR should prioritize workflow alignment (especially approvals and data changes), employee self-service clarity, and how the portal supports day-to-day operations during peak payroll periods.
Request an itemized proposal that includes licensing, implementation/configuration, integration effort, training, support tiers, and any optional modules. Compare total cost of ownership over a realistic multi-year timeline.
Look for evidence of implementation methodology, testing approach, security documentation, support model, and how responsibilities are shared between your organization and the supplier.
Very solutions can integrate, but the level of integration readiness varies. Confirm data mappings, validation rules, integration error handling, and whether your key workflows will run end-to-end as designed.
Require end-to-end testing, data quality validation, audit trail demonstration, training for administrators, employee communications planning, and clear cutover/go-live responsibilities.
By using controlled workflows and maintaining audit logs for key actions, a portal can make it easier to evidence payroll processing steps, approvals, and changes—assuming configuration and retention settings are implemented correctly for your requirements.
A common risk is under-scoped integration and testing. If upstream data quality issues, approval logic, or reconciliation steps are not fully validated, payroll errors and operational disruptions can follow.
A Payroll Solutions Portal can be a practical advantage when it is implemented with strong governance: clear roles, validated integrations, end-to-end testing, and a user experience that employees can actually use. By treating pricing as total cost of ownership, evaluating suppliers through delivery evidence, and confirming requirements in a structured workshop, organizations can reduce payroll friction and improve transparency across HR and finance.
If you approach selection as an operational design exercise—rather than a feature comparison—you’ll be better positioned to choose a portal that fits your workflows today and remains manageable as your organization changes.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
The Guide to Car Trading
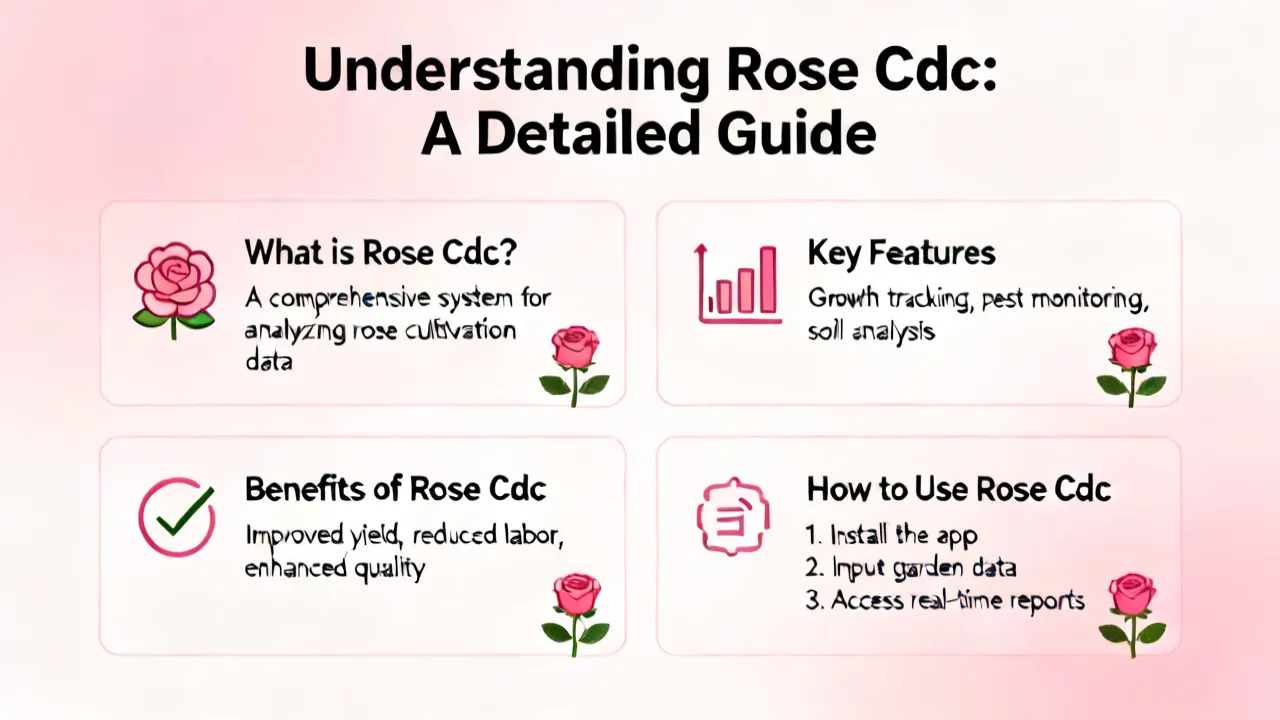
Understanding Rose Cdc: A Comprehensive Guide
This article provides an in-depth exploration of Rose Cdc, a term rapidly gaining attention in specific industries. Our discussion delves into the significance and application of Rose Cdc, its potential impact on various sectors, and expert insights into its future developments. This comprehensive analysis is designed to inform readers about the multifaceted aspects of Rose Cdc, its current applications, and potential advancements.
Understanding Compliance and AML Strategies
This article delves into the intricate realm of Compliance and Anti-Money Laundering (AML) strategies, highlighting their significance in the corporate world. Compliance AML refers to the organizational adherence to legal standards and regulations to deter financial crimes, ensuring transparent and ethical financial practices. This comprehensive guide examines these strategies' complexities and their pivotal role in safeguarding economic integrity.
Mastering Inbound B2B Strategies
The foundation of successful B2B strategies often lies in the effective implementation of inbound marketing techniques. In today's globally connected business environment, inbound B2B strategies have become critical for companies seeking to engage target audiences, optimize lead generation, and establish long-lasting partnerships. Understanding these strategies is essential for companies aiming to thrive in competitive markets.
Exploring B2B MBA Opportunities
Dive into the dynamic world of B2B MBA programs, designed for professionals seeking to enhance their strategic and management skills in a business-to-business context. This comprehensive guide discusses the significance of B2B MBAs in today's market, highlighting how these programs equip leaders with the expertise to navigate complex B2B relationships and drive business success.
Understanding Whitewater Regenerative Blowers
Whitewater Regenerative Blowers are essential in various industrial applications for their efficiency in moving air and gases. These blowers are known for their durability and ability to operate continuously, making them a preferred choice for industries ranging from wastewater treatment to aquaculture. This article explores their features, benefits, and applications, offering readers a comprehensive understanding of their importance in modern industry.
Mastering Employee Retention Strategies
Employee retention has become a critical aspect of organizational success, particularly in the dynamic landscape of 2020. As businesses strive to maintain a stable and productive workforce, understanding effective retention strategies is essential. This article delves into key methods for enhancing employee satisfaction and retention, offering a comprehensive guide for HR professionals and business leaders alike.