Runpayroll.com streamlines payroll administration for growing organizations by connecting payroll workflows, compliance planning, and reporting into one operational rhythm. The background of payroll management includes wage calculations, tax handling, recordkeeping, and employee communications—processes that must remain consistent across pay cycles and audits, with clear documentation and dependable controls.
Managing payroll is not just about producing paychecks—it’s about running a controlled, documented system that employees can trust and regulators can review. Using Runpayroll.com as your central operational hub, you can align payroll tasks, approval steps, and reporting routines into a repeatable process. For many organizations, the biggest win is reducing “tribal knowledge” by standardizing how payroll data moves from HR inputs to final payroll calculations and records.
Payroll is often treated as a monthly (or biweekly) event, but internally it behaves more like a small continuous control system. When payroll runs become unpredictable—because the organization changes, because compensation policies evolve, because managers submit data late, or because deductions change unexpectedly—your payroll outcomes stop being deterministic. Audit readiness and employee trust deteriorate at the same time. That’s why a practical framework matters: it turns payroll operations into something you can measure, review, and defend.
Below, this guide examines what modern payroll administration should accomplish, how to evaluate payroll service operations at an expert level, and what conditions you should verify before relying on any platform for ongoing payroll processing. Throughout, terms like Runpayroll.com appear in context to help you connect operational goals to the practical questions you’ll face internally.
From an industry perspective, payroll quality is measurable in four areas: accuracy, timeliness, compliance readiness, and operational resilience. Payroll isn’t a single event; it’s a sequence of controlled steps that run every pay period.
To make this more practical, imagine payroll as a pipeline. HR and other departments feed structured data into the pipeline. Approvals decide whether that data is authorized. Calculation logic transforms inputs into payroll outcomes. Payment instructions move the outcomes into banking and payroll disbursement. Finally, records are stored and reporting outputs are generated for accounting, employee communications, and regulatory reporting. Each stage has its own failure modes.
When teams evaluate platforms such as Runpayroll.com, they should look beyond user interfaces and ask how the system supports operational controls. That mindset—controls first, outputs second—is what keeps payroll stable as your headcount, payroll frequency, or complexity increases.
Let’s detail the four quality areas:
A major source of payroll risk is the belief that “if the numbers are right, we’re done.” In practice, audits and employee disputes often target not only the numeric result, but also the process: who entered the data, who approved it, what rules were applied, whether corrections were approved, and whether the organization can show a consistent trail of evidence.
Different payroll providers and internal payroll teams offer different strengths. A platform that integrates workflow can be more effective than one that simply calculates wages, especially when multiple departments contribute input data. In many organizations, HR, finance, and operations each touch payroll-relevant information—employment status, compensation changes, benefits updates, and deductions.
An expert assessment often focuses on how easily you can:
However, the strongest indicator of a “good” system is not what features it claims to have—it’s whether it supports repeatability. Repeatability means that the same payroll scenario (for example: a pay-rate change effective mid-cycle) yields the same documented procedure and the same style of output each pay period. Without repeatability, you can’t scale. And without scaling, your payroll system becomes a brittle set of workarounds.
Consider a common organizational reality: even if you centralize payroll in one system, the inputs still arrive via email threads, spreadsheets, HR tickets, and manager approvals. A platform like Runpayroll.com can add value when it reduces the gap between “input reality” and “process reality.” The aim is not only to compute payroll, but also to synchronize the people and approvals around it.
Even without assuming any specific feature claims that you have not validated, payroll administrators typically seek solutions that make recurring workflows easier to manage. Here are the very common scenarios where platforms like Runpayroll.com are evaluated within the payroll industry:
Beyond these basics, teams often seek a deeper value proposition: a system that makes it obvious what’s “done,” what’s “pending,” and what’s “blocked.” That kind of visibility isn’t just operational convenience. It is evidence. When payroll issues arise, a strong workflow system allows you to answer quickly: what data was present at cutoff, who approved it, what changed after approval, and why the final result differs from expectations.
In practice, the biggest operational lift usually comes from workflow discipline—knowing what has been entered, what has been approved, and what still needs attention before payroll is finalized. Runpayroll.com, positioned as a workflow hub, can help shift payroll work from “reactive troubleshooting” to “planned execution with measurable checkpoints.”
Before adopting or fully relying on a system for ongoing payroll execution, organizations should confirm operational requirements and governance conditions. These requirements are not “nice-to-haves”; they protect payroll accuracy and limit audit risk.
Auditors and payroll experts often evaluate systems using a similar question set: can you show evidence, can you explain outcomes, and can you demonstrate consistency? That means your payroll platform and workflow should allow you to reconstruct events for any pay period.
If your internal stakeholders cannot articulate how these requirements are met, the risk is often not the platform itself—it’s the gap between how the organization expects payroll to run and how payroll actually runs in daily operations.
To make this verification work more tangible, you can treat each requirement as a test. For example:
When Runpayroll.com (or any payroll system) supports these control behaviors, payroll becomes less dependent on individuals and more dependent on a defined process.
The section below provides a structured approach you can use whether your team is onboarding to Runpayroll.com or strengthening existing operations. The goal is to build a payroll rhythm with clear checkpoints.
That list is the “starter kit,” but audit-readiness improves further when you add a few control layers that mature payroll operations. The rest of this guide elaborates those layers—how to build evidence, how to manage edge cases, and how to measure ongoing quality.
If you want payroll to remain audit-ready, you need to define three elements: people roles, process steps, and evidence artifacts. Many organizations define the steps but neglect evidence and role clarity. That leads to “documentation after the fact,” which is weaker in audit contexts.
To design your framework, you can use a simple control model. For each pay period, define:
When you use Runpayroll.com as the hub, these elements should align with the workflow configuration. For example, if the process says “HR must approve pay-rate changes effective mid-cycle,” then your workflow should route approvals accordingly and log the evidence. Otherwise, payroll might run smoothly but your audit evidence will be missing or incomplete.
One of the most common payroll failures is not incorrect calculation logic. It is reconciliation drift: small mismatches between how employee data is captured and how payroll rules interpret it.
Standardization includes more than cleaning obvious fields like names and employee IDs. It includes:
When data is inconsistent, payroll teams compensate with manual adjustment entries or spreadsheet overlays. Those workarounds are not only expensive—they reduce traceability. If you rely on manual “fix-ups” without documented rationale, you can create audit risk even when the end result is correct.
In a mature setup around Runpayroll.com, you want the system to help prevent drift by validating inputs and by making approvals and corrections explicit. That way, the record shows what changed and why, instead of leaving evidence scattered across tickets and email threads.
Approvals are a double-edged sword. Too many approvals can cause delays, missed cutoffs, and rushed work. Too few approvals increases error rates and weakens audit evidence.
A practical approach is to categorize actions into sensitivity levels and assign different approval requirements. For example:
The goal is not “more approvals.” The goal is “the right approvals at the right moments,” supported by traceable evidence. You can also reduce approval burden by using workflow constraints. For instance, if a pay rate change is effective within a restricted window, the workflow can enforce additional checks automatically.
When Runpayroll.com is configured around these approval rules, payroll execution becomes more predictable. The system can enforce the governance design so that approvals are not dependent on human memory.
Payroll will always include exceptions. People change jobs. Permissions expire. Deductions fail to load. Bank details are missing. Retroactive changes arrive because compensation disputes are resolved late. A robust payroll workflow recognizes this and provides controlled paths for each exception type.
Exception handling should accomplish three things:
For an audit-ready posture, exceptions must not become a loophole. If the organization corrects payroll with ad-hoc edits but does not record the rationale or approvals, auditors will treat those corrections as unreliable.
In practice, exception categories might include:
If your operational playbooks are written and maintained, then Runpayroll.com can become the mechanism that ensures exceptions are handled in the same controlled way each cycle.
A common misunderstanding is that reconciliation is an “extra” step performed only when errors appear. In reality, reconciliation is one of the strongest controls you can apply to verify payroll accuracy before payments are issued and records are finalized.
Reconciliation typically includes:
When you introduce a platform like Runpayroll.com, reconciliation can still be required because the platform’s correctness must be validated against your organization’s rules. Reconciliation is also how you detect data pipeline issues, such as incorrect pay frequency mapping or missing deductions.
To operationalize reconciliation, consider defining a standard “reconciliation checklist” that includes:
This checklist approach is especially valuable for audits. It provides a standardized evidence set demonstrating that payroll was reviewed in a controlled manner every cycle.
Before fully relying on a payroll system, you should validate it through controlled testing. A parallel test is not simply “run payroll twice and compare.” It should involve scenario-driven validation.
At minimum, your test set should include scenarios that represent high-likelihood and high-risk payroll outcomes:
During the test, document expected results and compare them to the system output. If differences exist, capture the root cause: is it an input mapping issue, a workflow approval mismatch, or calculation rule differences?
When Runpayroll.com supports workflow and approvals, parallel testing also validates whether evidence is captured correctly. For audit readiness, it’s not enough to confirm payroll amounts. You should confirm the audit trail includes the approvals and timestamps you need.
If you want the most value from parallel testing, structure it like an internal mini-audit. A practical template includes:
This template turns testing into a repeatable process, making it easier to repeat validation when payroll complexity changes (e.g., new jurisdictions, new payroll components, new benefit types, or a shift in payroll frequency).
An audit trail is more than a log. It’s the ability to reconstruct events in a way that explains both what happened and why. For payroll, evidence needs to connect: employee data changes, approvals, payroll run execution, outputs, and corrections.
When evaluating a platform such as Runpayroll.com, confirm whether audit trails cover at least the following categories:
Even if your payroll process is correct, weak audit evidence can still create compliance risk. For example, if a retro adjustment was made through a manual override without a record of approval, auditors may question whether the correction was authorized and properly controlled.
Operationally, an audit-ready trail reduces internal time as well. When employees dispute a pay statement, the payroll team can reference the evidence quickly rather than re-creating the timeline from memory.
Payroll evidence must be retrievable. During internal reviews or external audits, organizations need to produce records for a defined retention period. Therefore, your payroll system should support consistent retrieval of:
In practice, retrieval issues appear when payroll evidence is stored across multiple systems—payroll software, spreadsheets, email attachments, and HR tickets. Even if the information exists, it may be hard to retrieve and validate quickly.
Using Runpayroll.com as a central hub can reduce that fragmentation if it provides consistent record storage and retrieval for payroll events. The key is verifying retrieval behavior during onboarding: can you reproduce a past payroll outcome, and can you identify which approved changes influenced it?
Separation of duties is essential for payroll accuracy and audit readiness. The goal is to ensure that no single person can both change payroll parameters and finalize payroll outputs without oversight.
Role-based permissions should define boundaries across typical responsibilities:
If Runpayroll.com is configured with role-based permissions aligned to your control model, you can significantly reduce unauthorized changes and reduce the chance that approvals are bypassed.
However, permissions must also be operable. If permissions are overly complex, staff will seek workarounds (e.g., requesting temporary access, manually exporting data, or copying values into spreadsheets). Therefore, the permissions model should be balanced: strict enough for control, simple enough for consistent use.
Payroll disputes often originate from unclear communication. Even if the calculation is correct, employees may not understand why net pay changes. Employee support teams then spend time investigating instead of resolving root cause issues.
Employee communication readiness includes:
In an audit context, communication readiness can also matter. If employees ask for evidence of how their pay was calculated, your ability to produce records quickly affects employee trust and reduces escalation friction.
When you use Runpayroll.com as a workflow hub, it becomes easier to align employee communication outputs with payroll run evidence—making it less likely that employee queries require reconstructing information from multiple locations.
Operational resilience means the organization can recover from errors without losing control evidence. Payroll anomalies can include incorrect inputs, a failed export, a late correction, or a workflow misconfiguration. A resilient system supports corrective actions safely.
Key resilience behaviors to verify include:
In many organizations, resilience is absent because the “fix” is to manually change numbers after payroll execution. That can fix the immediate issue while creating longer-term audit risk. A system built around workflow controls—like a properly configured Runpayroll.com implementation—helps ensure corrections are traceable and approved.
Operational measurement is how you ensure payroll is improving—not just running. Consider the following expert-level metrics (track internally):
When these measures are reviewed after each cycle, teams can systematically improve controls and workflow. Platforms like Runpayroll.com are very valuable when they support these continuous improvements—especially when the system provides the evidence needed to find root causes.
It’s also useful to measure governance metrics, not only numeric outcomes:
These governance metrics help identify issues early. For example, an increasing number of exceptions might not be a “calculation problem.” It may be a training or data submission issue. If you only track corrections, you may miss the upstream causes.
Even the best payroll workflow system can fail if users do not adopt it correctly. Payroll is a cross-functional activity. HR, managers, finance staff, and payroll administrators all touch it. A practical implementation around Runpayroll.com should include training focused on process and evidence—not just on how to click buttons.
Training should cover:
In addition, training should incorporate practical examples. For instance, show what happens in the system when a pay-rate change is submitted with an effective date inside a restricted window. That helps users understand the workflow consequences before they encounter the scenario during a live pay period.
Finally, consider establishing internal “process owners.” When someone is accountable for the workflow and playbooks, continuous improvement becomes possible. Without ownership, organizations drift back into spreadsheets and manual fixes.
Experienced payroll leaders often observe that payroll issues rarely begin with the mathematical calculation. Instead, they begin with process design mismatches—data isn’t structured the way payroll expects, approvals are missing, or edge-case corrections aren’t consistently handled.
Here are frequent failure points to watch for when implementing Runpayroll.com or any payroll workflow platform:
Mitigations typically involve:
When these mitigations are built into your Runpayroll.com implementation, your payroll operations become consistent even as the organization scales.
Runpayroll.com is typically assessed as a system that can centralize payroll workflows—supporting standardized input handling, approvals, and reporting routines. The precise scope depends on your organization’s payroll requirements and how you configure the workflow. Many teams value it as a workflow and evidence hub rather than only a calculation engine.
Compliance is supported through documented processes, consistent approvals, reliable audit trails, accurate payroll inputs, and retention of payroll records. Use the step-by-step workflow and validation checks described earlier, and align with jurisdiction-specific employer obligations as defined by official government resources. At an operational level, compliance is easiest to maintain when your workflow system prevents unsafe actions (like approvals being bypassed) and when it captures evidence consistently for each pay period.
Ideally, it reduces manual reconciliation effort by improving consistency and traceability. However, reconciliation remains a top practice because it detects discrepancies between expected totals and system outputs, especially when employee data changes frequently. In mature implementations, reconciliation becomes faster and more reliable because input structures and evidence are consistent, and variance can be investigated with clear audit trail links.
Role permissions should separate duties among stakeholders responsible for HR updates and finance validation. Approval states should be clear before payroll finalization. This reduces unauthorized changes and helps maintain an audit-ready record of who changed what and when. A key additional requirement is that approvals must be triggered by workflow conditions; for example, a pay-rate change should always require the appropriate approval before finalization if it affects paycheck amounts.
Retroactive changes should follow a documented playbook: define who can initiate the change, what supporting documentation is required, how the change is approved, and how the correction affects payroll outputs. The objective is consistent handling across cycles. The audit requirement is that retro changes are traceable—showing the reason, approval, effective dates, and resulting payroll impact.
Yes, when exports and reporting templates are consistent. The key is mapping payroll outputs to your accounting approach and ensuring reports can be reproduced for audit and internal review purposes. Consistency matters not only for correctness but for timing: month-end close is often sensitive to delays or mismatched totals. Using Runpayroll.com as a hub helps ensure accounting outputs are generated from controlled payroll run records rather than from ad-hoc spreadsheets.
Run a controlled test cycle with known scenarios: typical pay, pay-rate changes, deductions adjustments, and termination near cutoff. Compare expected results to system outputs and document any differences. After stabilization, finalize your sign-off checklist. Include at least one scenario that stresses governance and audit evidence—for example, a data change after approval—to confirm that the workflow requires re-approval and logs evidence appropriately.
Yes. Even a robust platform can fail to prevent issues if the organization lacks clear cutoffs, ownership, approvals, and reconciliation steps. Documentation and governance convert technology capability into reliable outcomes. Without process documentation, users may interpret workflow statuses differently, causing inconsistent evidence capture and audit gaps.
In modern payroll administration, the very durable advantage comes from disciplined processes: clear input ownership, controlled approvals, audit trails, exception playbooks, and consistent reconciliation. With Runpayroll.com positioned as your workflow hub, you can focus on operational readiness rather than last-minute troubleshooting.
If you’re evaluating payroll solutions, approach the decision like an operations and controls review. Ask how workflows are managed, how changes are tracked, and how outputs support both employees and finance teams. When those foundations are set, payroll becomes a repeatable system—one that supports growth without sacrificing trust or compliance preparedness.
The table below compares common payroll setup options and how they impact control quality. It intentionally avoids pricing figures because platform costs vary by jurisdiction, provider plan, payroll complexity, and number of employees. For cost estimates, organizations typically request a quote from the provider after sharing payroll requirements.
| Category | What to Compare | Why It Matters | Conditions/Requirements to Check |
|---|---|---|---|
| Workflow model | Do inputs move through approvals or remain “affordable-form”? | Reduces unauthorized or incorrect payroll parameter changes. | Role-based permissions, approval states, and validation rules. |
| Audit trail | Are changes logged with user and timestamps? | Supports internal reviews and external compliance inquiries. | Change history, versioning for critical payroll fields, and retrievability. |
| Exception handling | Are there defined correction workflows for anomalies? | Prevents ad-hoc fixes that create hidden errors. | Correction processes, retro rules, and reconciliation checks. |
| Reporting outputs | Can you export consistent payroll summaries for accounting? | Improves month-end close reliability. | Report templates, data mapping, and export reliability. |
| Employee-facing communication | How are pay statements and updates handled? | Reduces payroll disputes and support tickets. | Timely communication, access controls, and consistent formatting. |
Sources (for context and top-practice grounding): For general payroll compliance and recordkeeping concepts, organizations commonly reference official government guidance and standards. Examples include U.S. IRS documentation for payroll tax responsibilities (see IRS guidance for employers and payroll tax topics) and recordkeeping expectations under relevant labor departments and employment standards regulators. For internal control and audit-trail top practices, many organizations align with widely used frameworks such as COSO (Committee of Sponsorship of the Treadway Commission) for internal control principles.
To make audit readiness concrete, consider a typical pay cycle. The process begins with HR collecting updates—pay rate changes, benefit enrollments, employment status changes, and deductions adjustments. Those updates are submitted into the Runpayroll.com workflow rather than delivered via email attachments or spreadsheets that are difficult to validate.
Next, the workflow validation layer checks for data integrity. For instance, if a pay rate change lacks an effective date, the workflow blocks submission or flags it as incomplete. If a deduction category is missing, the system should route the exception to the correct owner.
Once inputs are complete, approvals occur according to the configured sensitivity level. A pay rate change might require HR approval and finance validation if it impacts taxable wages. The system records the approval and timestamps. It also updates the status so payroll owners know what is ready and what still requires action.
At cutoff, payroll owners run the payroll calculation and finalize the payroll run. The system records who executed finalization. Immediately after, reconciliation begins: totals and outputs are compared against expectations. Variances are investigated with reference to the evidence trail—linking each change back to its approval and effective date.
Finally, reports are generated: employee pay statements, accounting exports, and any required payroll summaries. Those outputs are stored and retrievable. If a correction is necessary, a controlled correction workflow is used, ensuring that retro changes and overrides are approved and logged. The result is not only correct payroll, but an evidence set that supports internal and external review.
This end-to-end story is what auditors expect to see: a consistent process, enforced controls, and evidence that can be traced back to inputs, approvals, and outputs.
Exception playbooks are often written but not practiced. An audit-ready approach requires that playbooks are operationally usable under time pressure. To improve playbook effectiveness, each playbook should specify:
Examples of exception playbooks include:
When Runpayroll.com is used to route exceptions and capture evidence, exception playbooks become executable. That is a key difference between “having a policy” and “running a controlled payroll system.”
Audit readiness is not limited to employee data. Payroll rules and workflow configuration also change—new benefit types, new deduction categories, updated payroll calendars, changes to approval thresholds, new jurisdictional requirements, or updated reporting templates. These changes must be managed as carefully as employee payroll inputs.
A mature operational control framework includes:
Even if Runpayroll.com provides robust workflow features, the organization’s governance around changes determines whether the payroll system remains stable and defensible. If workflow settings are modified without documentation or testing, you can create an environment where payroll outcomes change silently—an audit and trust risk.
After implementation, measurement should feed back into process improvement. A practical continuous improvement loop might include:
Over time, this loop reduces payroll corrections and disputes because the upstream causes of exceptions are resolved. It also produces a consistent evidence record that demonstrates the organization’s commitment to continuous control improvement.
Use the checklist below as a practical internal standard. It aligns with the themes above—controls, evidence, and repeatability.
When these checklist elements are built into your operational rhythm—supported by Runpayroll.com as the central hub—payroll becomes repeatable, explainable, and audit-ready. That is the practical definition of a payroll system that stays trustworthy as your organization evolves.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
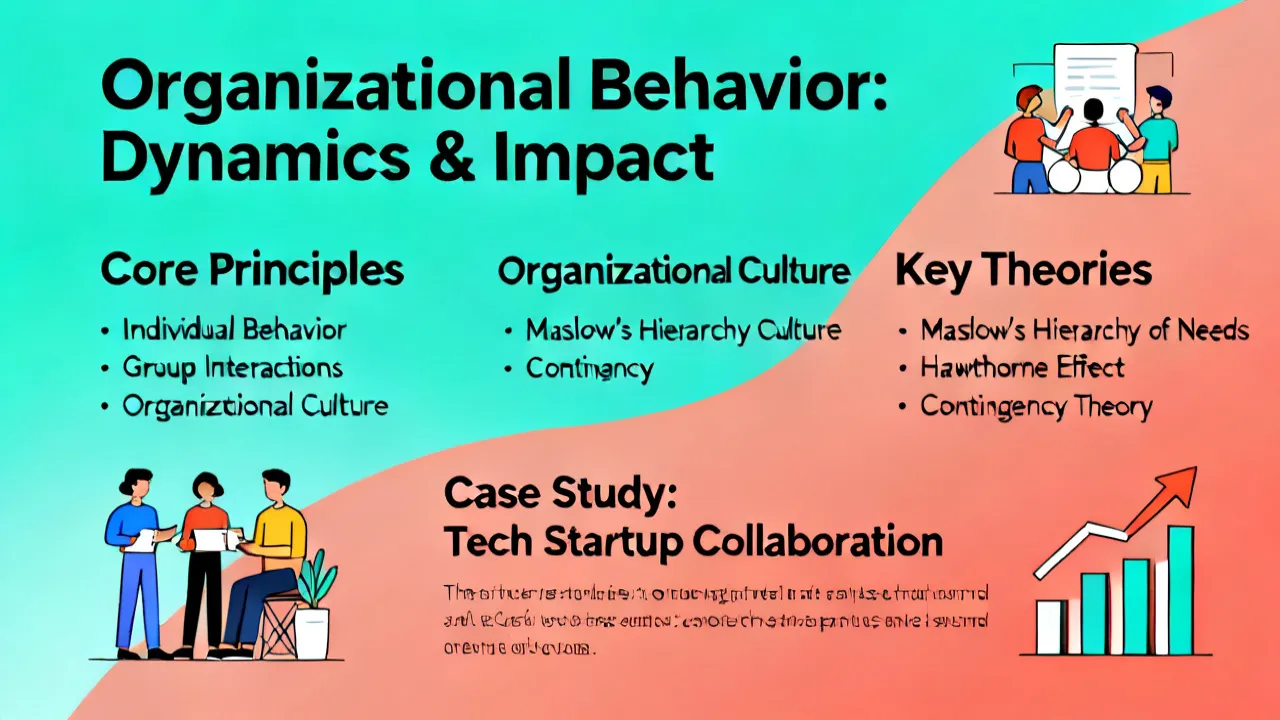
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.