This guide explains how Avidxchange can work with QuickBooks to strengthen accounts payable (AP) workflows, improve invoice visibility, and reduce rework across teams. It then provides objective background on the two platforms and why AP automation matters for finance operations, including common integration considerations and implementation themes.
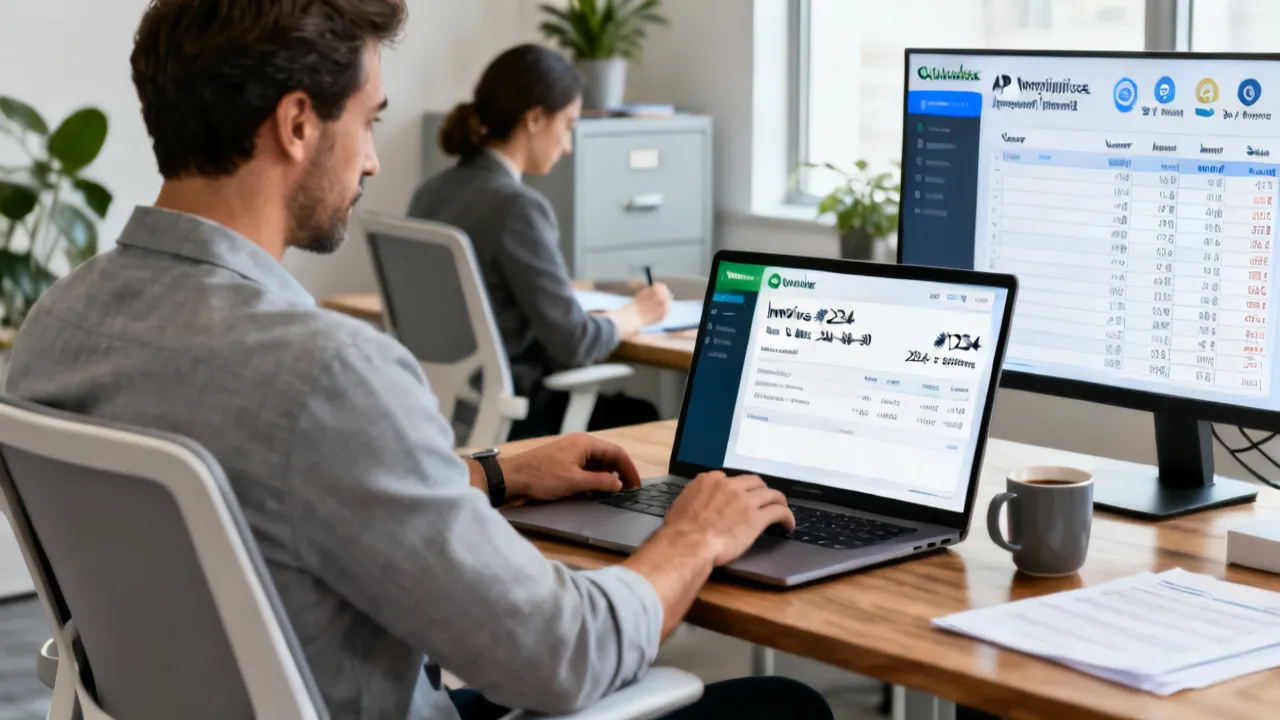
Integrating Avidxchange with QuickBooks can help finance teams streamline the flow of invoices, approvals, and posting activity—so accounts payable (AP) becomes more predictable and easier to reconcile. In practice, the very valuable outcome is tighter coordination between the invoice lifecycle (capture, routing, approval, payment-ready status) and the accounting ledger inside QuickBooks. When configured carefully, teams typically experience fewer “spreadsheet detours,” clearer audit trails, and more consistent posting behavior across periods.
From an industry perspective, the integration is not just a technical connection; it is an operational redesign of how work moves from procurement and accounts payable into the general ledger. That operational angle matters because even a well-built integration can fail to deliver results if invoice coding, approval policies, and exception handling are not defined up front.
In other words, a “good integration” is rarely measured by whether data can technically move between systems. The real question is whether the move preserves the intent of the invoice—what it is for, how it should be classified, how approvals were documented, and when it becomes eligible to impact the ledger. In many finance organizations, the pain points being targeted by Avidxchange Quickbooks search intent are less about software capability and more about reducing ambiguity in process ownership and control.
When integration decisions are made late—after AP operations have already standardized workarounds—teams often end up preserving the old ambiguity inside the new workflow. That can show up as duplicate data entry, re-keying after exceptions, inconsistent coding practices among approvers, or delayed recognition of invoices during month-end close. Conversely, when integration is used to harden workflow governance—making “what happens next” explicit and enforceable—the system becomes a control framework as much as it becomes a productivity tool.
AP sits at the intersection of procurement commitments, vendor communications, and accounting accuracy. When invoice data changes between teams—e.g., approvals happen in one place and posting happens in another—errors and delays are more likely. The combination of Avidxchange Quickbooks as a search intent typically reflects a goal: unify the operational steps so finance can close faster and respond to vendor and internal questions with less friction.
For a neutral, objective framing, consider what “better” usually means in AP operations: invoices are captured once, validated against rules, routed to the correct approvers, and then posted to the correct accounting structure with minimal manual intervention. Integration with QuickBooks can serve as the accounting “source of record” while Avidxchange can function as the workflow and decisioning layer.
Consistency is not simply about having fewer errors. It is about predictability. In predictable systems, finance teams can answer routine questions quickly, such as: Which invoices are pending approval? Which are approved but not yet posted? Which are blocked by missing tax data? Which invoices will fall into the current period versus the next? When those answers become easy to obtain, AP stops being a reactive function during close and becomes a controlled process.
Additionally, workflow consistency supports compliance and internal control. Approvals and coding are often treated as control points—ways to ensure that only authorized transactions get recorded and that they are recorded in the correct accounts. If the approval logic is inconsistent or the ledger entry is not reliably tied to approved invoice data, internal controls become harder to evidence. This is where integration is particularly relevant: it creates a more complete lifecycle story, rather than a fragmented set of documents.
However, consistency only emerges when key decisions are standardized. For example, if different AP analysts code departments or classes differently, the integration can still function, but postings may become inconsistent. If vendor data is inconsistent, the integration might correctly route invoices but still fail validation rules. If approval thresholds are unclear, invoices may bounce between approvers or stall in a way that delays posting eligibility. Therefore, the “integration changes” are ultimately workflow changes: teams adjust how they classify, route, review, and resolve.
Very organizations explore Avidxchange Quickbooks to address recurring bottlenecks:
Importantly, the integration’s impact depends on how AP teams configure vendor profiles, mapping rules, and approval requirements. If these foundational items are inconsistent, the operational “handoff” into QuickBooks can still require corrections—sometimes in a different form than before.
To see where value is created, it helps to think in terms of stages. A typical invoice stage progression in an AP workflow looks like: intake → extraction/validation → coding → approval routing → approval completion → ready to post → posted to ledger → paid and matched (in some cases). Integration changes the way these stages align with the ledger. Without integration, organizations often manage ledger entry with manual spreadsheets or batch uploads. With integration, organizations can align “ready to post” status with the posting step more tightly—reducing the time gap where invoices exist in one system but not yet reflected in the other.
That alignment can have a compounding effect. When invoices are posted correctly and on time, reconciliation effort drops. When reconciliation effort drops, AP analysts have more bandwidth to resolve exceptions promptly—leading to even better timeliness. Conversely, if exceptions accumulate due to poor validation and mapping, postings become unreliable, reconciliation worsens, and the process becomes less predictable.
So the integration adds value when it acts as an enforcement mechanism for your business rules. It becomes particularly valuable for organizations with a high invoice volume, multiple departments, and varying vendor types (e.g., recurring services, project-based billing, utility providers, professional services, or one-time vendor invoices). In these environments, small inconsistencies scale quickly.
In professional services and mid-market operations, “integration” usually refers to a repeatable process where invoice and payment status updates flow between an AP automation platform and the accounting system. In the Avidxchange Quickbooks context, the accounting platform is often used to record and report financial activity. Meanwhile, an AP automation platform can manage workflow steps and standardize invoice handling.
From a governance standpoint, the critical question is whether integration produces a single, consistent lifecycle record. For example: does the system preserve invoice numbers, vendor references, tax treatment, and allocation detail reliably when moving from workflow to ledger posting? If the answers are well managed, finance teams can spend more time on review and exceptions rather than on routine corrections.
Another aspect of industry context is that “integration” often also means “operational handoff.” Many organizations use one system as a staging area for information and another system as the ledger. Without a consistent integration strategy, information may be duplicated in multiple places, or it may be transformed in ways that are not obvious to reviewers. A well-designed integration reduces the number of “semantic transformations”—for instance, where invoice line coding becomes a ledger line coding, and those transformations must be predictable and reversible when issues arise.
It is also common that integration can create new control dynamics. For example, if the workflow system blocks posting until approval and required fields are complete, then QuickBooks entries may only be created after review. That shift affects how teams think about who “owns” the transaction at different times. In an integration-heavy model, ownership can move from AP operations to approvers to finance reviewers, with the workflow system acting as the state machine of the transaction.
Yet it is essential to remember that QuickBooks, by itself, is not an AP workflow engine. QuickBooks excels at recording and summarizing transactions but does not provide the same workflow governance. Integration aims to combine QuickBooks’ accounting strengths with Avidxchange’s workflow strengths. The change is not simply technical—it is about distributing responsibilities more deliberately.
Before implementation, teams generally benefit from validating requirements in these areas. This is where many “integration expectations” either align—or diverge—from reality.
These elements are more influential than very teams expect. In many successful deployments, finance leadership emphasizes process design first, configuration second.
To add clarity, each of these areas deserves deeper thought:
When these areas are handled early, integration becomes less fragile. When they are deferred, teams often face “fix it later” work that can be more expensive during stabilization and worse during close periods.
You may encounter varying figures when researching Avidxchange Quickbooks because pricing models often depend on implementation scope, transaction volume, user count, payment methods, and the depth of configuration. Because pricing is not included in your prompt, the very objective approach is to treat “price” as a range of cost drivers rather than a single number.
From an industry-expert standpoint, the practical way to evaluate total cost is to ask for a pricing proposal that clarifies:
This avoids assumptions and helps you compare options on comparable terms. It also supports procurement governance, because vendor proposals can be evaluated against a documented business case.
It is also useful to think beyond “license cost” and include operational costs. Integration projects can require internal resources for mapping validation, vendor master data cleanup, approver training, and cutover planning. Even if those hours do not appear on an invoice from the vendor, they affect total cost of ownership.
A practical way to approach this is to request a cost breakdown that includes:
Additionally, ensure that the contract clarifies the responsibilities for data mapping and troubleshooting. Some vendors provide accelerators and templates, while others rely on your team to provide business logic. Clarifying that early reduces surprises later.
The supplier or vendor dimension is often overlooked. Even with strong workflow tooling, invoice accuracy and timeliness depend on how vendors submit invoices and how well their invoice details align with your internal coding and approval expectations.
In objective terms, vendor readiness generally involves:
If your supplier base is heterogeneous, you may expect more exceptions early on, followed by smoother processing as rules and data patterns stabilize.
In practice, “vendor readiness” includes both data and process. Data readiness means invoices are structured consistently enough for extraction and validation. Process readiness means invoices arrive with enough lead time to support approvals and posting before cutoffs. Some vendors invoice monthly; others invoice per milestone; others invoice irregularly. Integration can help, but it cannot fully compensate for a vendor base that provides invoice information inconsistently or late.
A helpful strategy is to categorize vendors into groups (e.g., recurring contracts vs ad hoc suppliers) and align integration validation rules accordingly. For example, high-volume recurring vendors often justify stricter automated coding rules, while one-time vendors might use more flexible validation with a higher exception rate. This approach prevents the system from stalling in an attempt to apply overly rigid rules to data it cannot reliably satisfy.
Additionally, vendor communications should be coordinated with internal policy. If AP expects a vendor to include a billing period or PO reference, your procurement team should reinforce that expectation. Otherwise, you may train the system to accept missing fields, reducing the value of automation and increasing manual follow-up.
The following is a supplement to the main discussion. Because your request asks for conditions/requirements slightly later in the article, the guide and comparison are placed here.
| Area | Avidxchange (AP workflow role) | QuickBooks (accounting ledger role) | Key Requirement / Condition |
|---|---|---|---|
| Invoice intake | Captures and routes invoices through workflow steps | Receives posted accounting impact for reporting | Invoice data fields must align to your posting rules (vendor, amounts, references) |
| Approvals | Manages approval routing and status transitions | Does not replace approvals; it records the result | Approval thresholds and coding logic should match internal policy |
| Posting behavior | Determines what is ready to be posted | Records transactions in the general ledger | Account mapping and tax treatment must be configured before go-live |
| Exceptions | Flags issues for review or correction | Reflects corrected or approved accounting entries | Define exception handling workflows to avoid delayed close |
| Audit trail | Preserves evidence of approvals and invoice lifecycle | Supports reporting and ledger traceability | Invoice identifiers and documentation retention rules must be consistent |
What makes this guide “typical” is the underlying logic of modern AP systems: the workflow system handles state and governance, while the accounting system handles recording. The conditions that matter most are those that control state transitions and data transformations. If a state transition occurs without correct data (e.g., missing tax code), you can end up with ledger entries that require reversal or manual corrections. If a state transition is blocked incorrectly (e.g., approvals configured too strictly), invoices may wait unnecessarily, impacting vendor relationships and close timing.
Therefore, the integration path should always include validation and testing phases that specifically target those state transitions. A robust test plan verifies not only that data can be posted, but that the “why” behind posting is preserved: approval outcome, coding decisions, and tax treatment.
To make this sequence more actionable, consider how to “operationalize” each step. Documenting your current AP process is not only listing steps—it should include identifying the data fields that matter and the control points that prevent unauthorized postings. When you define mapping standards, include examples. Mapping documentation should contain real sample invoices and show how each invoice line will map into QuickBooks accounts and classes. If you only describe mapping in abstract terms, you risk misalignment between AP expectations and accounting structures.
When preparing vendor master data, decide on a governance process for updates. For example, who approves changes to vendor tax settings? Who ensures vendor names remain consistent when procurement adds a new location or remit-to account? Integration systems often enforce rules more uniformly than manual processes did; without governance, new data can create exceptions.
For approval rules, it is useful to include “edge case” scenarios. Examples include invoices that contain multiple departments, invoices above thresholds but coded differently, or invoices that include credit memos. Approval logic should account for these scenarios and clearly define whether approval is required at line level or invoice level.
When configuring validation rules, teams should define what “failure” means. Is missing a PO number a failure or a warning? Is missing tax code a failure that blocks posting? These decisions impact operational throughput. A strict validation approach can reduce posting corrections but can also create high exception rates that overwhelm AP reviewers. A lenient validation approach improves throughput but increases the risk of inaccurate ledger postings. Integration success often depends on finding the right balance.
In the pilot phase, do not limit testing to happy paths. Test invoices that are likely to fail extraction or that contain unusual line items. Also test “timing” behavior around period close. For example, what happens if an invoice is approved on the last day of the period but extracted earlier? How does the system decide which QuickBooks period to post to? These timing questions can strongly affect close outcomes.
Success conditions extend beyond configuration. Named ownership is critical. Integration projects often stall not because the technology fails but because there is no clear decision maker for exceptions. If an invoice fails mapping rules and no one knows whether AP should correct coding or whether finance should adjust mapping rules, the workflow can become stuck. That results in delayed postings and reduced trust in the system.
Training for reviewers should include how to interpret workflow status and how to use the integration’s audit trail. Reviewers should understand what data fields are authoritative for posting. They should also be taught how to recognize when a failure indicates a data quality issue versus a configuration gap.
Additionally, stable accounting structure is often underestimated. Even when the Chart of Accounts is stable, changes can occur in classes, departments, or tax code behavior. Integration teams should create a “change control” process. Change control does not necessarily mean no changes—it means changes are tested and communicated with enough lead time so mapping rules and approval logic remain consistent.
Finally, realistic go-live planning means acknowledging the transition period. During go-live, the organization may run both old and new processes for a short time. Or, it may switch to the new integration and still use manual backstops for a time. Whatever approach you choose, planning should include a buffer for issue resolution. Integration issues during close can damage confidence quickly.
While individual outcomes vary, organizations commonly see improvements in:
However, these benefits are not automatic. They typically require disciplined configuration, governance, and process adherence.
To expand on these benefits in practical terms, consider how each manifests in daily AP operations.
It is also worth noting that integration can improve vendor experience indirectly. When invoices are processed faster and with fewer manual delays, vendors experience fewer questions and fewer disputes about status. While integration is internal, its effects can be external because AP processing time often affects vendor perceptions.
In addition, better lifecycle data can support forecasting and reporting. If AP leaders can identify which invoices will post in the next period, they can improve cash planning. Even if cash forecasting is not an immediate goal, the improved data quality can help finance teams refine planning processes over time.
To remain objective, it’s important to acknowledge typical friction points when implementing a Avidxchange Quickbooks style integration:
Mitigation usually comes from the same disciplined steps: better master data, documented rules, a pilot phase, and a clear exception process.
Challenges often come from the real-world variability of invoices and internal governance. For example, invoice extraction may interpret certain fields incorrectly when vendor templates vary. That can lead to wrong coding decisions or missing required fields. Teams mitigate this by using validation rules that detect extraction confidence issues, by training reviewers on how to correct extracted fields, and by adjusting mapping rules based on observed invoice patterns.
Approval rule ambiguity is another common problem. It may not be obvious at the beginning that approval thresholds vary by spend type (e.g., travel vs office supplies) or that approvals should depend on cost center or project ownership. If approval rules are overly simplistic, you can inadvertently route invoices to the wrong approvers or to too broad a group. Mitigation involves revisiting procurement authority matrices and translating them into workflow rules that the system can enforce.
Mapping mismatches can happen when organizations maintain a Chart of Accounts that works for financial reporting but does not align with operational invoice categories. If an invoice description suggests a department or project but the mapping requires additional structured fields, teams may experience frequent exceptions. Mitigation involves improving the invoice data provided by vendors (where possible), refining required fields on invoices, and potentially introducing standardized coding inputs (e.g., cost center or project identifiers) at intake.
Cutover complexity deserves particular attention. There are multiple cutover scenarios, such as:
Mitigation involves explicit cutover rules, communicated clearly to AP and finance teams. For example, you may decide that all “in-flight” invoices follow the old process, or you may migrate them into the new workflow with a controlled method. Whatever decision is made, it should be documented and tested in a pilot-like scenario if possible.
Finally, integration challenges often lead to trust issues if not managed carefully. If AP reviewers experience repeated failures or unclear status behavior, they may bypass the system, creating a shadow workflow. The goal of mitigation is not just to fix configuration errors but to ensure the operational experience is stable enough that teams adopt the workflow confidently.
It generally connects invoice workflow and approval status handling with accounting posting in QuickBooks, so invoices move from intake through review and then reflect in the ledger based on configured mapping rules.
Very teams still handle exceptions and judgments manually—especially for invoices with unusual line items, missing fields, or mismatched vendor information. The goal is usually reduced rework and clearer workflow rather than total automation.
Not necessarily, but your Chart of Accounts and mapping rules must be compatible with how invoice coding should be posted. If your accounts are structured in a way that doesn’t align with how invoices are categorized, you may need adjustments or new mapping logic.
In a well-designed workflow, approvals act as a gate. Invoices generally move to “ready for posting” only after required approvals are completed, helping ensure QuickBooks reflects authorized transactions.
Pricing commonly depends on scope, transaction volume, implementation effort, and configuration needs. For accurate budgeting, request a written proposal that itemizes onboarding and ongoing cost drivers.
Start with vendor master data cleanup and onboarding standards. Consistent vendor naming and required invoice fields reduce mismatches and lower the volume of exceptions during and after integration.
Yes. Many organizations begin with a limited set of vendors or invoice types to validate posting accuracy, tax behavior, and approval workflows. This improves confidence before scaling.
Integration projects often focus heavily on “getting the invoice to post,” but long-term value depends on how data can be used for reporting, control, and continuous improvement. Even if initial posting works correctly, teams should plan for how they will monitor performance and ensure that the system continues to enforce governance as invoice patterns evolve.
For finance leaders and AP managers, the post-go-live phase should include monitoring routines. These routines might include tracking the percentage of invoices that fail validation, the number of invoices corrected manually, the median time from invoice intake to posting, and the distribution of invoice exceptions by category (e.g., missing PO, tax mismatch, coding ambiguity). Over time, these metrics become a diagnostic tool that helps refine mapping rules and validation logic.
Another consideration is how reporting will be handled. QuickBooks is useful for ledger-based reporting, but Avidxchange may provide workflow-level reporting (e.g., approval status and workflow stage). The integrated approach ideally provides a consistent narrative from workflow status to ledger impact. Teams should clarify which system will be the reference for which type of reporting. For example, AP leaders might use Avidxchange for operational dashboards, while accountants use QuickBooks for financial reporting.
Consistency in reporting reduces the risk of conflicting numbers. Without clear definitions, teams can experience frustration when Avidxchange and QuickBooks show different counts or amounts for the same time period. This is often not a data error—it can be a timing difference (e.g., invoice extracted but not yet posted). However, if the organization does not establish common definitions for statuses and posting timing, stakeholders may misinterpret the results. Therefore, governance should include reporting definitions and training.
Control is also influenced by integration design. If approvals are a gate, and if posting occurs only after approvals, then the system supports a strong control model. But control can degrade if there are loopholes—such as users with excessive permissions who can post bypassing workflow states, or exception paths that allow posting without adequate review. Post-go-live governance should include permission reviews and periodic audits of exceptions.
Continuous improvement is the final dimension. Integration rules will not remain optimal forever. Vendor invoice templates change, AP policies change, procurement authority matrices evolve, and accounting changes can occur. Mature finance organizations treat integration configuration as living business logic, not as a one-time setup. That means having a change management process, documented rule ownership, and periodic re-validation against real invoice samples.
One of the most significant integration changes is how workflow governance is represented and enforced. In traditional AP processes, controls may rely on human memory, manual checklists, and spreadsheet-based tracking. Integration shifts those controls into the system—into the workflow states, required fields, approval rules, and exception logic.
When governance is properly designed, the system can enforce the “sequence of authority.” For example, no invoice should reach the posting stage unless approvals are complete and required coding is present. This reduces the likelihood of unauthorized ledger entries. It also creates a clearer audit trail, because approvals become structured evidence rather than informal records.
However, governance design must be careful to avoid creating new failure modes. A strict governance model can halt workflow when input data is incomplete. If exception resolution is slow, strict governance can become a bottleneck during close. Therefore, governance must include both enforcement and responsiveness. Enforcement ensures integrity; responsiveness ensures throughput.
A practical approach is to classify exceptions into severity levels. For instance:
With severity levels, you can route exceptions to the appropriate reviewers and decide whether posting should be blocked or whether it can proceed after review. This transforms exception handling from a single undifferentiated queue into a controlled process, which is critical for close readiness.
Another governance element is permissions. Integration may allow different user roles: AP reviewers, approvers, finance controllers, and system admins. Permissions should align with responsibilities. Approvers should ideally confirm and approve without being able to alter accounting coding unless policy allows it. AP reviewers should have limited tools to correct data, but corrections should be traceable. Admins should manage mapping changes through a controlled workflow to prevent accidental rule changes.
In a mature integration, governance also includes data integrity checks. For example, you might require that invoices containing certain categories post to specific accounts. The system can enforce these rules. This reduces reliance on individual reviewer expertise and makes the process more consistent.
Cutover is where many integration projects experience their most stressful days, because it involves timing and state transitions. Even well-prepared teams can face surprise issues if the organization does not explicitly decide how to handle invoices that are already in motion during go-live.
Common cutover patterns include:
Each pattern has advantages and disadvantages. Freeze-and-flush can reduce complexity but may affect vendor experience if intake is paused. Dual processing can maintain throughput but increases the chance of confusion and duplicate records. State migration can preserve workflow continuity but requires careful data mapping and testing.
Regardless of the pattern chosen, cutover documentation should include specific rules. For example:
It is also important to define communication channels. AP and finance teams need to know who to contact when an invoice fails during the transition. Many integration failures during cutover are not configuration errors; they are policy or data readiness issues. Having an escalation path prevents a queue from growing.
Finally, cutover should include a checklist and a sign-off process. Sign-off might involve confirming that mapping rules are tested, vendor master data is ready, required fields are enforced, and exception workflows are active. Ideally, this sign-off occurs before a close period begins, because close introduces immovable deadlines.
Mapping is the practical engine of integration value. In AP workflows, invoices often contain unstructured descriptions, line items with varying categories, and tax information that may be represented differently across vendors. The integration must translate this into QuickBooks accounting structures.
To better understand mapping, consider a few realistic scenarios and the types of decisions mapping rules must support.
Scenario A: Multi-line invoices with multiple departments or classes
An invoice might include several line items, each tied to different departments. If your QuickBooks setup uses classes or departments, mapping rules must support allocation across these dimensions. If mapping relies on a field extracted from the invoice, but that field is absent for some lines, those lines may fail validation. Teams can mitigate this by requiring additional structured fields for such invoice types or by using exception workflows that route partial mapping issues appropriately.
Scenario B: Service invoices with billing periods
Service vendors often invoice for work performed during a specific billing period. If your accounting policy requires that expenses be recognized in the correct period, then the integration must align invoice dates or service period dates to QuickBooks posting rules. Mapping rules should define how to select the posting date (e.g., invoice date vs billing period). Even if the integration posts successfully, if the date alignment is wrong, month-end reporting will be misleading.
Scenario C: Tax-inclusive vs tax-exclusive invoices
Some vendors provide tax-inclusive totals with tax lines, others provide pre-tax totals with tax codes. If QuickBooks expects tax to be coded a certain way, integration rules must select the correct tax treatment. Validation rules should detect inconsistencies and route them to reviewers rather than allowing incorrect postings. This is one of the most common sources of ledger corrections during AP transitions.
Scenario D: Credit memos and refunds
Credit memos can be as complex as invoices. They may reduce expenses in the ledger, require different approval handling, and potentially affect cash or tax accounts differently. Integration should define whether credit memos are treated as negative invoices, how they post to accounts, and how approvals work. Testing credit memos in the pilot phase is essential.
Scenario E: Invoices with missing identifiers
Some invoices may omit PO numbers, contract references, or invoice numbers. Integration workflow typically relies on invoice identity for audit trails and reconciliation. When invoice identifiers are missing, the system needs a policy: reject the invoice, request additional information, or assign a temporary identifier under controlled conditions. The chosen policy affects audit readiness and reconciliation complexity later.
These scenarios show why mapping is not just technical—it is policy. The more your integration is configured to follow your policies, the more predictable posting will be. The less your rules reflect actual policy, the more manual corrections you will see after invoices hit QuickBooks.
Exception workflows are where integration projects succeed or fail operationally. An integration that posts only “perfect” invoices may appear to work during testing, but in real operations, invoices rarely arrive perfectly formatted. The integration must provide a controlled pathway for exceptions so that AP reviewers can resolve them quickly and that accounting results remain correct.
Exception handling should include:
From a close-readiness standpoint, exception workflows also require throughput planning. If too many invoices end up in exceptions at go-live, reviewer teams can become overwhelmed. The system should be configured to avoid excessive failure rates by using appropriate validation rules.
However, relaxing validation rules can reduce exceptions but increase the risk of inaccurate posting. That’s why a balanced design is needed. Teams often mitigate this tradeoff by tightening rules gradually. During pilot and early rollout, validation rules may be less strict for low-risk invoice fields and stricter for high-risk fields like tax and coding accounts. Over time, once data quality is proven, rules can become stricter.
Another important exception aspect is the ability to handle bulk corrections. If many invoices from the same vendor fail the same mapping rule due to a vendor format change, reviewers should be able to correct the rule once rather than correcting each invoice individually. That requires good exception tagging and review workflows.
Training is frequently treated as a logistical step, but in integration projects, training is actually part of control design. If reviewers do not understand the workflow states and the meaning of approval completion, they might behave in inconsistent ways. Inconsistent behavior can undermine the integration’s goal of standardized posting and predictable lifecycle tracking.
Training should cover:
Because different roles use the system differently, role-based training is often more effective than one-size-fits-all sessions. AP reviewers need practical workflows and correction procedures. Approvers need understanding of what they approve and what that means for ledger posting. Finance administrators need how mapping rules and vendors are governed.
Adoption also depends on trust. If reviewers experience unpredictable results—such as invoices posting with incorrect accounts or exceptions that are difficult to resolve—trust erodes quickly. Building trust requires early support during initial rollout and a structured approach to refining rules based on observed outcomes.
After go-live, the integration becomes a living system. New vendors appear, invoice formats shift, internal accounting policies evolve, and procurement rules change. Without ongoing governance, mapping rules can drift out of alignment with real business processes.
A healthy governance model includes:
Metrics help identify where integration value is actually being realized. If exception rates remain high months after go-live, it can indicate mapping rules are not aligned with the invoice mix. If approvals fail to occur before close deadlines, approval rules might be too strict or approver coverage might be insufficient.
Governance should also include documentation. When audits or internal reviews occur, documentation reduces reliance on tribal knowledge. Mapping rule documentation, approval matrix documentation, and exception workflow documentation provide transparency.
Finally, governance should include contingency planning. Systems can be disrupted by configuration errors, data mismatches, or vendor changes. Having an incident response approach—who checks what first, how to temporarily route invoices, and how to ensure ledger accuracy during incidents—reduces operational risk.
At a conceptual level, AP automation platforms are designed to manage the lifecycle of invoices from receipt to approval and payment readiness. Accounting systems like QuickBooks are designed to record financial transactions and support reporting and reconciliation. When these two capabilities work together, finance teams can separate “workflow governance” from “accounting recording” while maintaining a consistent linkage between invoice events and ledger impact.
From an operational top-practice perspective, AP automation is often discussed alongside the broader finance transformation themes seen across industries: improving control, reducing cycle time, strengthening auditability, and increasing visibility of financial activity. These themes are commonly reflected in technology and operations research from established firms and industry bodies.
For example, process automation and AP digitization are frequently analyzed in reports by organizations such as McKinsey & Company (finance transformation themes), AP and invoice automation research from industry analysts, and publications from recognized accounting ecosystems. For the specific impact of workflow digitization on error reduction or processing speed, readers should rely on the very relevant, recent studies for their industry segment and operational baseline.
It is also useful to think about integration as part of a broader operating model. Many finance transformations include shared services, process standardization, and analytics capability. Integration contributes by making the workflow data and ledger data consistent enough for reporting and analytics.
However, that analytics readiness depends on data quality. If mapping rules are inconsistent or vendor identifiers vary, the quality of downstream analytics suffers. Therefore, integration should be viewed as enabling capabilities—like better reporting and control—only when underlying data governance is established.
Because your prompt does not include specific numerical performance claims or pricing figures, this article avoids unverified statistics. When considering any vendor performance assertions, it’s recommended to reference primary vendor documentation, implementation case studies, and third-party research from reputable industry analysts (e.g., consulting research or analyst reports) and to validate outcomes against your own invoice mix and AP cycle metrics.
General background themes on finance process improvement and automation can be found in widely cited research from organizations such as:
In addition to referencing sources, teams should validate assumptions internally. For example, if your organization believes integration will reduce close time, it should measure close-related metrics before and after go-live. These metrics might include the number of late postings, the number of ledger corrections, or the median time for exceptions to be resolved.
Another validation approach is to test the workflow logic on a representative sample of invoices. The best “proof” is operational: does the integration behave correctly for your invoice mix and your approval rules? Testing avoids reliance on generalized claims that may not reflect your specific coding and tax requirements.
If your organization is searching for Avidxchange Quickbooks integration guidance, the clearest path to value is not just “connecting systems,” but designing a workflow that produces clean, auditable inputs for the ledger. When invoice validation, approval policies, and account mapping are treated as first-class requirements—and tested through a controlled pilot—finance teams can typically improve operational consistency and reduce the manual effort required to keep AP and accounting aligned.
Ultimately, the integration changes you should expect are operational: how decisions are made, how exceptions are handled, and how quickly ledger impact becomes reliable. When those operational changes are grounded in governance, the integration can become a durable improvement rather than a one-time implementation project.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Unveiling RS Sul Telecom Services
RS Sul Telecom emerges as a prominent entity in the telecommunications industry, providing reliable services across various regions. This article delves into the offerings of RS Sul Telecom, the benefits it presents to both individual and business clients, and its impact on the modern telecom landscape.

Understanding Rlock Advpl in Business
Rlock Advpl represents a pivotal advancement in business software solutions, offering enhanced security and efficiency for enterprise resource planning systems. This article delves into the intricacies of Rlock Advpl, its application in modern businesses, and the benefits it offers in streamlining operations and safeguarding data. As an expert tool, Rlock Advpl is essential for businesses looking to optimize their IT infrastructure.

Unveiling Atranet Innovation
Atranet represents a cutting-edge concept in networking technology. Harnessing its capabilities can transform digital communication by providing seamless connectivity. Designed to optimize data transfer, security, and efficiency, Atranet is shaping the future of how we connect and share information. This article delves into its structure, applications, and potential impacts on industry practices and consumer experiences.

Understanding Polysulfide Adhesive Applications
This comprehensive guide explores the applications and benefits of polysulfide adhesive, highlighting its unique properties and widespread use in construction, aerospace, and automotive industries. Known for its flexibility and resistance to various environmental factors, polysulfide adhesive is a key component in sealing and bonding applications, providing durability and reliability in demanding conditions.
Comparing Vtex with Salesforce Commerce
This article provides an in-depth comparison between Vtex and Salesforce Commerce, two leading digital commerce platforms. Each offers unique features suited to different business needs. Vtex is renowned for its collaborative commerce approach, while Salesforce Commerce shines with its comprehensive customer relationship management capabilities. Explore their differences, strengths, and insights from industry experts.
Understanding the Latest Chrome Version
This article delves into the intricacies and features of the latest Chrome version. Chrome, developed by Google, is one of the very popular web browsers globally, known for its speed, simplicity, and security features. Each update aims to enhance user experience through improved functionality and performance. Understanding these updates is crucial for both everyday users and developers.